Author: wricefinancialgroup
FX Report 2026 Week 36
Executive Summary
Week 36 was shaped by a volatile U.S. labor-market data flow, the largest single-currency spot move of the week in the Japanese yen, and a rates market that visibly recalibrated around Friday’s employment report. Spot FX activity was concentrated at the extremes of the major-currency set: the yen posted the week’s strongest performance against the dollar while the Swiss franc was the softest. CME derivatives data showed FX futures and options participation building steadily through the week, with activity increasingly concentrated in EUR and JPY products. A soft ADP private-payrolls print mid-week gave way to a considerably stronger-than-expected nonfarm payrolls report on Friday, and CME Treasury options activity shifted from a put-dominant to a call-dominant composition over the same span. The Bank of Canada held its policy rate steady, even as Canada’s own Friday employment report disappointed sharply alongside a strong Ivey PMI reading. Treasury and short-term rate developments are discussed below primarily for their bearing on currency positioning, hedging conditions, and corporate financial risk.
Foreign Exchange & Options
Spot Performance and Relative Strength
Weekly spot performance was uneven across the major pairs. USD/JPY declined 1.99% for the week — the largest move among the six pairs tracked — placing the yen as the strongest major currency of the period; the pair also showed weak technical readings (a “sell” rating with an RSI near 33), consistent with sustained downward pressure through the week rather than a single-day event. At the other end, USD/CHF rose 0.69%, the strongest weekly gain in the set, making the franc the weakest major currency; technical readings for USD/CHF were firmly on the buy side. EUR/USD and GBP/USD each softened modestly (-0.33% and -0.50% respectively) but remain in positive territory over the trailing one- and three-month windows. USD/CAD was little changed (-0.13%), and AUD/USD posted a small weekly gain (+0.17%) that sits within a much stronger medium-term uptrend (+7.87% year-to-date).
Futures and Options Activity
CME FX futures activity built progressively over the week. Aggregate futures open interest rose each day, from roughly $292 billion on Monday to $319 billion by Friday — a gain of about 9%. Daily futures notional volume climbed from about $79 billion on Monday to a mid-week peak near $151 billion on Thursday before easing to $129 billion on Friday. Euro and yen futures remained the two largest products throughout the week by a wide margin, and both grew faster than the broader market: yen futures notional roughly doubled (from about $21 billion to $34 billion) and euro futures notional grew by a comparable proportion, concentrating an increasing share of total futures activity in the two currencies that also produced the week’s most notable spot moves.
Options activity told a related but distinct story. Total FX options notional volume rose from about $2.7 billion on Monday to $5.3 billion on Friday. Euro options remained the largest single component in dollar terms, but their share of total options notional fell from roughly 71% to 51% over the week as yen options notional grew nearly six-fold in relative share (from about 10% to 31% of the options total), concentrated heavily in short-dated (about one-week) expirations. Within euro options, put notional continued to exceed call notional across the week and became more concentrated at the October monthly expiration, where put notional grew from roughly $576 million to $806 million — consistent with increased demand for downside optionality in EUR at that later date rather than a directional call on the currency’s near-term path. This options activity should be read as a measure of hedging, speculative, and volatility-related participation; it is not, on its own, evidence of market expectations for currency direction.
Treasury and Rates
U.S. Treasury futures volume declined steadily through the week, from about 8.3 million contracts traded on Monday to 5.6 million on Friday — a decline of roughly a third — while open interest was essentially unchanged across the period (around 22.8 million contracts throughout). Treasury options activity moved in the opposite direction on the volume side, rising into the back half of the week, and its composition shifted meaningfully: on Monday, put volume represented about 59% of total Treasury options volume, but by Friday call volume represented about 54% of the total, with the shift occurring around midweek. The 10-year note remained the most actively traded options product across the week in both directions.
CME’s SOFR reports showed daily futures and options volumes and open interest holding within a fairly narrow range across the week, without a clear directional trend in participation. The more notable development appeared in the SOFR futures settlement strip: on Friday, settlement prices declined versus the prior session across essentially every listed contract month, with the decline more pronounced at longer-dated maturities (roughly 3-4.5 basis points at the back of the strip versus roughly 2-2.5 basis points at the front). A broad, longer-maturity-weighted move of that kind is consistent with a market digesting new information about the rate outlook, though the CME data alone does not establish what specifically drove it.
The week’s economic calendar supplied the likely macro backdrop for much of this rate-market activity. U.S. ADP private payrolls missed expectations badly on Wednesday (38,000 versus a 47,000 forecast, with the prior month revised down), while ISM Services PMI beat solidly on Thursday (55.4 versus 54.2 expected) even as ISM Manufacturing PMI missed on Tuesday (54.6 versus 55.2, still in expansion territory). Friday’s nonfarm payrolls report then came in well above expectations (162,000 versus a 55,000 forecast, with the prior month revised sharply higher to 21,000), while the unemployment rate held at 4.1%. In Canada, the Bank of Canada held its overnight rate at 2.25% as expected on Wednesday, but Friday’s employment report showed a sharp decline in Canadian jobs (-41,700 versus an expected gain of 15,100) alongside a strong Ivey PMI reading (64.3 versus 56.2 expected) — two releases pointing in different directions on the same day. Eurozone inflation data showed a similar internal tension: core CPI cooled slightly more than expected (2.4% y/y versus a 2.5% forecast) while headline flash CPI ticked up to 3.3% y/y from 2.9% previously. Swiss CPI surprised meaningfully to the upside (0.4% m/m versus a flat forecast), and Bank of England Governor Bailey delivered remarks on Friday for which no transcript was available in this week’s source materials.
Cross-Market Takeaways & WFG Perspective
- Yen strength was accompanied by a genuine build in yen-specific derivatives participation. USD/JPY’s outsized weekly decline coincided with the sharpest relative increase in both futures and options notional activity of any currency in the set — a case of derivatives participation confirming, rather than diverging from, the week’s clearest spot move.
- Euro spot was comparatively quiet even as euro options positioning shifted further toward downside protection at the October expiration. A modest weekly decline in EUR/USD occurred alongside growing put concentration further out on the calendar; the two developments are consistent with each other but the options data do not establish that the growth in downside hedging caused, or was caused by, the modest spot move.
- Rates-market positioning shifted over the same week that U.S. labor data sent conflicting signals. The move in CME Treasury options from put-dominant to call-dominant, and the broad, back-end-weighted decline in SOFR settlement prices on Friday, occurred alongside a soft ADP report followed by a strong payrolls beat — a sequence consistent with markets adjusting rate-market positioning as the data evolved, though CME’s activity data alone cannot confirm the specific driver.
- Canada’s Friday data presented a genuine divergence — a sizeable employment decline alongside a strong Ivey PMI — yet USD/CAD moved only modestly for the week. The muted spot reaction may reflect the offsetting nature of the two releases rather than a clear market verdict on either one.
- Treasury futures participation cooled through the week even as Treasury options volume and euro/yen FX notional activity built into Friday. The supplied data establish this divergence across products but do not indicate a specific cause; it is noted here as a pattern worth monitoring rather than an explained relationship.
What This Means for Businesses
Companies with material euro exposure — particularly those with payables or receivables settling around early-to-mid October — may want to review hedge coverage extending into that window, given the growing concentration of downside-protection activity at the October expiration alongside a comparatively quiet spot euro.
This was the most active week of the period for yen positioning, both in spot terms and across futures and options. Businesses with near-dated JPY commitments, or hedge programs sized around calmer historical conditions, may benefit from confirming that current hedge ratios and horizons remain appropriate.
The dollar’s strongest weekly gain among the majors was against the Swiss franc. This move may warrant reviewing CHF hedge coverage and upcoming payment exposures in light of the currency’s technical weakness over the week.
Canada’s split data picture — a sharp jobs decline alongside a strong business-activity reading — points to continued monitoring of incoming Canadian data before drawing conclusions about the near-term outlook for CAD-linked exposures.
The shift in Treasury options positioning and the broad, longer-maturity-weighted move in SOFR settlement pricing this week are modest developments individually, but together support a routine review of floating-rate exposure and related hedge documentation ahead of upcoming Federal Reserve-relevant data.
WFG Market & Corporate Risk Monitor
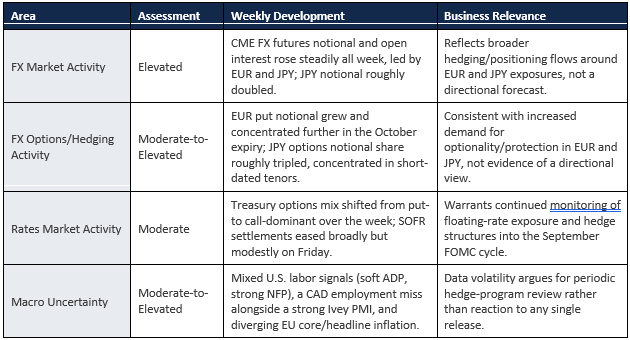
These are qualitative WFG assessments derived from the week’s available source materials, not quantitative risk scores or trading signals.
FX Report 2026 Week 35
Executive Summary
Actual currency performance this week was modest. The U.S. dollar strengthened slightly against all six major currencies tracked, ranging from essentially unchanged against the Australian dollar to a 0.89% advance against the Swiss franc, with the euro, British pound, Japanese yen, and Canadian dollar each softening by roughly 0.6%–0.75% against the dollar. That measured price action stood in contrast to a substantial rise in FX derivatives participation: CME FX futures notional volume rose approximately 74% over the week (from $53.9 billion to $93.6 billion), and FX options notional volume more than quadrupled ($2.25 billion to $9.83 billion), concentrated overwhelmingly in the euro.
Within FX options, the euro and Swiss franc — the week’s two weakest currencies in spot terms — also showed the clearest shift toward put-side (downside) positioning: EUR put share of options notional rose from 56% to 76%, and CHF options flipped from call-led to put-led. By contrast, the Australian dollar was essentially flat in spot terms despite persistently put-tilted options activity, and the yen softened only modestly even as its options activity remained call-tilted throughout — a reminder that this week’s options positioning did not move in lockstep with spot price for every currency.
In U.S. rates, SOFR futures and options volume both surged on Friday alongside a continued decline in SOFR settlement prices across the curve, consistent with a rise in near-term implied rates. Treasury activity told a more two-sided story: Treasury futures volume and open interest fell to their weekly lows by Friday, while Treasury options volume surged to a weekly high that same day and the put share of options activity — which had built for three straight sessions to a Thursday peak of nearly 59% — reversed to about 52% on Friday, most sharply in the 30-year sector.
The week’s macro backdrop centered on the three-day Jackson Hole Economic Symposium (August 27–29) and a Friday address from Fed Chairman Warsh, alongside a hotter-than-forecast Australian CPI print, a U.S. GDP Price Index reading above forecast, better-than-expected U.S. jobless claims, and a Canadian GDP beat paired with a much smaller downward U.S. payrolls revision than the prior period. For businesses with cross-border currency exposure or floating-rate financing, the combination of modest spot moves and sharply elevated derivatives participation argues for a hedge-coverage review — particularly for EUR and CHF exposures — rather than a reaction to outsized currency swings, which the data do not show.
1. Foreign Exchange & Options
Spot Performance
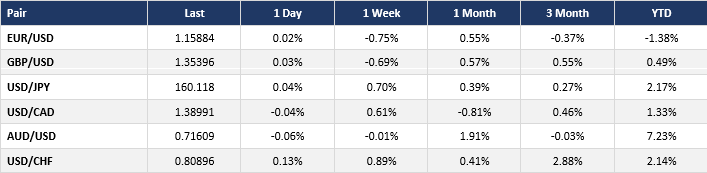
Spot price data (below) show broad but modest U.S. dollar strength this week. AUD/USD was essentially unchanged (-0.01%), the steadiest of the majors, while USD/CHF posted the week’s largest move (+0.89%, i.e. franc softening). EUR/USD, GBP/USD, and USD/CAD each moved 0.6%–0.75% against the dollar, and USD/JPY was little different, up 0.70%. None of these weekly moves were unusual relative to the pairs’ own 1-month and 3-month ranges, and technical readings across the majors were generally neutral to modestly favorable for the dollar side of each pair — including an elevated CCI reading on USD/JPY consistent with that pair’s well-established longer-term uptrend (USD/JPY is up 9.01% over the trailing year) — without signaling an extended or unusual move this week specifically.
Futures & Notional Activity
Beneath this comparatively modest price action, FX derivatives participation increased sharply. Aggregate CME FX futures notional volume rose from approximately $53.9 billion on Monday to $93.6 billion on Friday, with the euro accounting for 28%–43% of daily futures notional value and the yen a consistent second. The increase in participation, without a corresponding increase in spot-price movement, may reflect increased hedging, positioning, or event-related activity during a week that included the Jackson Hole Symposium and month-end positioning. The data do not establish a specific cause.
Options Positioning
FX options notional value rose from $2.25 billion on Monday to $9.83 billion on Friday, again led by the euro. EUR put notional value rose from roughly 56% of total EUR options notional on Monday to approximately 76% by Friday, increasingly concentrated in short-dated (within-one-week) expirations. CHF options flipped from call-led (57%) to put-led (58%) over the same period, alongside the week’s largest spot move. GBP put concentration, the most lopsided of the majors on Monday (85%), moderated to about 61% by Friday even as overall GBP options volume nearly tripled. AUD options remained consistently put-tilted (57%–58%) all week despite flat spot performance, and JPY options remained consistently call-tilted (52%–54%) despite the yen’s modest softening — in both cases, a divergence between options positioning and the week’s actual spot direction. As always, options activity of this kind can reflect hedging, speculation, or multi-leg strategies, and should not be read as a directional forecast.
2. Rates & Macro
SOFR futures volume held in a relatively narrow range from Monday through Thursday (3.15–3.60 million contracts) before jumping to 6.07 million on Friday, while SOFR options volume rose even more sharply, from 549,000 contracts on Monday to 2.30 million on Friday. SOFR settlement prices declined across nearly every point on the futures curve over the week, most pronounced in longer-dated contracts — consistent with a rise in the rate implied by the futures market. The SOFR options put/call balance shifted only modestly toward calls by Friday (56% versus 51% on Monday) even as volume on both sides rose several-fold, consistent with a broad-based increase in positioning activity rather than a one-sided shift.
Treasury futures volume and open interest both declined through the second half of the week, falling to their weekly lows on Friday (futures volume of 10.3 million contracts, down roughly 59% from Monday and 69% from Tuesday’s mid-week peak of 33.6 million). Treasury options activity moved differently: options volume surged to a weekly high of 1.83 million contracts on Friday, more than double Thursday’s level, even as options open interest eased from Thursday’s peak and the put share of options volume — which had risen for three straight sessions to 58.6% on Thursday — reversed to 52.1% on Friday, most sharply in the 30-year sector (43.5% to 28.8% put share). The pattern is more consistent with a burst of active repositioning coinciding with Friday’s scheduled Fed Chair remarks than with a sustained one-directional build in rate-market hedging.
The week’s economic calendar centered on the Jackson Hole Economic Symposium (August 27–29) and Fed Chairman Warsh’s Friday address, alongside a hotter-than-forecast Australian CPI print on Tuesday (headline CPI y/y of 3.5% versus 3.3% forecast), a U.S. GDP Price Index reading above forecast on Wednesday (6.4% versus 6.2%), better-than-expected U.S. jobless claims on Thursday (203,000 versus 208,000 forecast), and a Canadian GDP beat alongside a much smaller downward revision to prior U.S. payrolls figures on Friday. The source materials reviewed did not include the text of Treasury Secretary Bessent’s or Fed Chairman Warsh’s remarks, so this report does not characterize what was said in either appearance.
3. Cross-Market Observations
- The euro and Swiss franc were the only two majors where a weekly softening in spot price was accompanied by options activity that shifted toward, or remained concentrated in, puts by Friday — in the franc’s case, a shift from call-led to put-led positioning alongside the week’s largest currency move. This alignment is consistent with, though does not prove, hedging or positioning activity that anticipated or responded to the currency’s actual softening.
- By contrast, the Australian dollar was essentially flat for the week even though AUD options remained consistently put-tilted, and the yen softened modestly even though JPY options remained call-tilted throughout — two cases where options positioning did not track the direction of the week’s actual spot move, underscoring that options activity should not be read as a reliable predictor of near-term price direction.
- FX options activity reached its weekly high on Thursday and Friday, coinciding with the opening days of the Jackson Hole Symposium and Friday’s Fed Chairman Warsh remarks, even as the week’s actual currency moves remained modest — a pattern consistent with elevated hedging or positioning activity around a policy-communication event rather than an unusually volatile trading week.
- Treasury futures activity fell to its weekly lows by Friday while Treasury options volume surged and its put-share build partially reversed, whereas SOFR settlement prices continued their decline across the curve into Friday — suggesting the SOFR and Treasury markets may have processed Friday’s developments somewhat differently, a distinction worth continued monitoring.
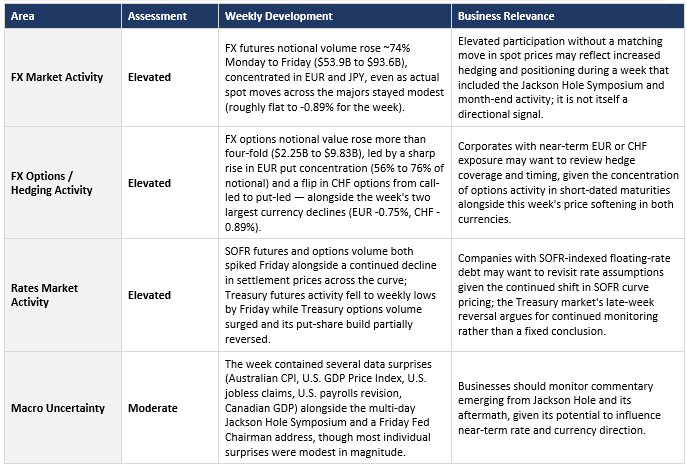
4. WFG Market & Corporate Risk Monitor
The assessments below reflect a qualitative reading of this week’s CME activity, spot-FX performance, and economic-calendar data; they are not derived from a quantitative risk-scoring methodology. Note that “Elevated” below describes market participation and hedging activity, not confirmed currency volatility — this week’s actual spot moves were modest, as detailed above.
5. What This Means for Businesses
This week’s actual currency moves were modest by historical standards — the dollar strengthened only slightly against most majors, led by a 0.89% advance against the Swiss franc and a 0.75% advance against the euro, while the Australian dollar was essentially unchanged. Beneath that modest price action, FX derivatives participation rose sharply, particularly in EUR and CHF options, where downside (put-side) activity became increasingly concentrated in short-dated expirations by week’s end. For companies with EUR or CHF payables, receivables, or budget exposure over the coming weeks, this combination — a real but modest currency move alongside a much larger increase in near-term hedging and positioning activity — may be a reasonable prompt to review existing hedge coverage and timing, without treating the week as evidence of a larger directional trend.
In the rates markets, SOFR pricing moved consistently through the week toward higher implied near-term rates, while Treasury market positioning was more unsettled, building through Thursday and partially reversing on Friday alongside a surge in trading volume coinciding with Fed Chairman Warsh’s scheduled remarks. Corporate treasurers with SOFR-indexed floating-rate debt or upcoming financing decisions may want to revisit rate assumptions in light of the SOFR curve’s move, while recognizing that Treasury-market positioning remains unsettled and may continue to evolve as Jackson Hole commentary is digested in the days ahead.